Investors are contemplating a new eurozone debt crisis after the euro hit a 17-month low against the US dollar. Concern has focused on France, where public debt stands at €3.596 trillion, equivalent to 119% of GDP. The yield on ten-year government bonds, known as “OATs”, approached 5% for the first time since 2002. The gloom is weighing on the local CAC 40 share index, which is down 6% over the past month.
In Paris, the remaining optimists argue that France just needs to follow Italy's example, says Eric Mengus in Les Echos. After years of struggle, Rome is running primary budget surpluses (that is, before interest payments). But that consolidation rested on a political consensus that is lacking in France, where major parties continue to cling to “illusions”. Many believe that the problem can be solved through new wealth taxes. The radical left calls to cancel parts of the debt outright in order to “make the banks pay”.
Back in the real world, primary deficit reduction of three to four percentage points is probably required to rein in the situation, yet the current government is struggling to get support for a budget that reduces the deficit by 0.6%.
Start your trial of MoneyWeek today
Get unparalleled financial insight, analysis and expert opinion you can profit from.
Start your trial
Sign up for MoneyWeek’s free twice-daily newsletter.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Eurozone at most risk since the 2012 crisis
The “old cliché” – that “France doesn't reform, it only has revolutions” – is being tested anew, says Simon Nixon on Substack. All eyes are on “Le Spread”, the gap between French and German government borrowing costs. This measure of eurozone risk has reached 1.4 percentage points, the highest level since the 2012 eurozone crisis. That remains far short of the levels seen by the likes of Italy and Greece during the eurozone crisis. And although rates have spiked, the legacy of years of ultra-cheap borrowing means interest expenses for Paris are still a modest 2% of GDP. But what is lacking is political will in a country that hasn't achieved an overall budget surplus since 1974.
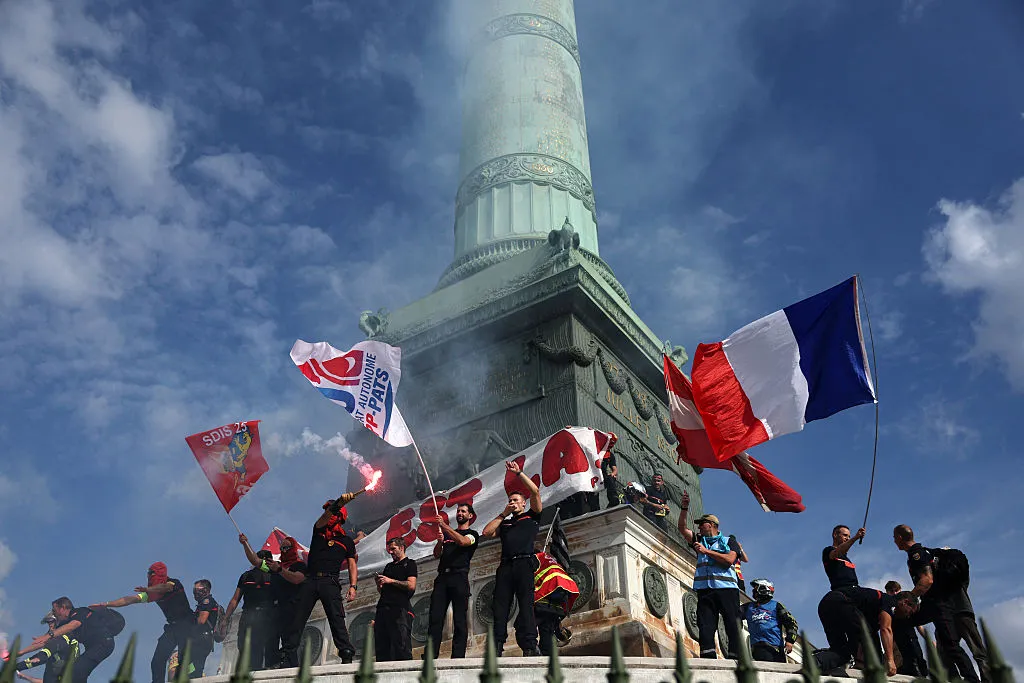
It doesn't help that France is out protesting again, this time about the lack of money for high schools, says the Financial Times.
Debt has risen by more than a trillion euros since Emmanuel Macron took office in 2017. The president's pro-business reforms failed to raise enough revenue to curb runaway spending. The European Central Bank (ECB) has been reluctant to get involved, but with the way things are going some think that it is “just a matter of time”.
Still, talk of 2011-style “contagion” across the eurozone is unwarranted, argues a note from asset managers DWS. The ECB and member states have developed a series of monetary tools and procedures that would make fighting another debt crisis much more orderly than in 2011. The continent's banks are also much better capitalised today. “France's fiscal problems are real,” but trouble in the eurozone is not necessarily trouble for the eurozone.
This article was first published in MoneyWeek's magazine. Enjoy exclusive early access to news, opinion and analysis from our team of financial experts with a MoneyWeek subscription.