Join more than 165,000 subscribers and keep yourself informed with the latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
You are now subscribed
Your newsletter sign-up was successful
Want to add more newsletters?
An account already exists for this email address, please log in.
Bonds look like the buy of the year. But don’t be too hasty...
Are corporate bonds as cheap as they look? Yields are certainly high enough, says James Ferguson, but it’s early days yet.
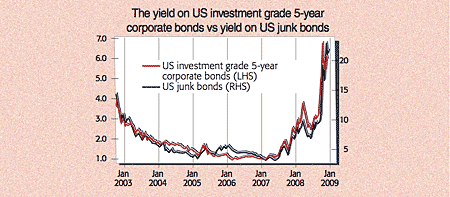
Are corporate bonds (CBs) as cheap as they look? Yields are certainly high enough. US active investment-grade five-year CBs (the red line on the chart), which means rated BBB or above, are yielding 7.35%. Junk bond yields (black line) are at a stratospheric 22.7%. Considering that coupons are fixed and bond holders rank ahead of all equity if a firm goes bust, these yields look great value compared to the 3.3% dividend yield and prospective 8.5% earnings yield (which is bound to disappoint) that the S&P 500 is offering.
Why is this happening? According to the FT, "assets everywhere are being dumped in favour of cash... corporate bonds are no longer that attractive as collateral for funding because counterparts are demanding more onerous terms in exchange for lending out cash in return." And the revelation that Bernard Madoff's funds, fraudulently valued at $50bn, could be worth just $300m, could lead to further forced selling of CB funds. But once this abnormal sell-off is complete, could corporate bonds offer the year's best investment opportunity?
At first sight, yes. After all, Barclays Capital says that US GDP would have to shrink by 15% to justify current bond spreads. Trouble is, this may not be that wide of the mark. A Bank of England study of 33 banking crises between 1977 and 2002 found that the average loss of output over the course of a crisis was a cumulative 23% of GDP. That worked out at roughly 7% of GDP growth a year being lopped off, compared to the trend of the previous ten years. What would that mean for the US? By late 2006, boosted by the last days of the credit bubble, US GDP had been running at a prior ten-year average growth rate of 3.2%. Since bank crises last more than four years on average, a flat GDP would only be a 13% cumulative loss from trend. That suggests that an actual loss of 10% of GDP would be about what we'd have to expect from this banking crisis based on past experience.
Try 6 free issues of MoneyWeek today
Get unparalleled financial insight, analysis and expert opinion you can profit from.
Sign up for MoneyWeek’s free twice-daily newsletter.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Of course, this is exactly what the US and UK governments' spending packages are meant to offset. Such a scenario may make you want to rethink equity exposure even more than CBs. But there are at least three other reasons why CBs may not be the great deal they seem to be. First, while they may be discounting huge default rates, they may also be reflecting the fact that when asset prices are falling, you don't recover as much money when bonds default. You'd usually expect to retrieve at least 50% of the value of a corporate loan from collateral sales. But with banks slashing lending, auction buyers can't get the credit they need to bid top dollar. So loan loss retrieval may be much worse than 50% this downturn.
Second, it's early days yet. AA-rated bonds, for example, may seem to have a very high yield. But that maybe because, in the market's mind, they're really CCC it's just that the ratings agencies (lagging indicators if ever there were any) haven't downgraded them fully yet.
Third, CB spreads may look wide compared to government bond yields. But that comparison is not valid in a banking crisis, where monetary policy effectively stops working. I'll explain why.
But the opposite also holds true when credit gets tighter and more expensive. In normal times, the government bond yield for any maturity (the risk-free rate) gives a reasonable indication of the cost of debt in the wider economy; you just need to add a small appropriate risk premium. As you can see from the chart, until recently, even five-year US junk bond yields were only 3% or so above the risk-free Treasury yield.
Yet once a banking crisis sets in, the government bond yield no longer bears any resemblance to the real world cost of debt. If you instead compare corporate bonds to assets other than government bonds, they are still cheap, but not nearly so out of kilter.
That said, they do rank above stocks and do seem to be offering some great yields. The risks are clearly heavily weighted towards a further increase in actual defaults, and a worsening of the retrieval rate in the event of default, so it's too risky targeting individual bonds or even portfolios with narrow investment criteria the risks will be too concentrated. A balanced approach is to look for funds with the widest possible portfolio spread to make the most of attractive yields, while taking the lowest possible specific default risk. Just don't be surprised if it turns out in the end that corporate bonds weren't quite as radically underpriced as some would have you believe.
James Ferguson is chief strategist at Pali International. He also writes the Model Investor newsletter.
Sign up for MoneyWeek's newsletters
Join more than 165,000 subscribers and keep yourself informed with the latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
James Ferguson qualified with an MA (Hons) in economics from Edinburgh University in 1985. For the last 21 years he has had a high-powered career in institutional stock broking, specialising in equities, working for Nomura, Robert Fleming, SBC Warburg, Dresdner Kleinwort Wasserstein and Mitsubishi Securities.