Join more than 165,000 subscribers and keep yourself informed with the latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
You are now subscribed
Your newsletter sign-up was successful
Want to add more newsletters?
An account already exists for this email address, please log in.
Three resilient Japanese stocks for growth and income
Three Japanese stocks picked by Richard Aston, a portfolio manager on the Chikara Japan Income & Growth Trust.
When picking Japanese stocks, our aim at the Chikara Japan Income & Growth Trust plc (formerly the CC Japan Income & Growth Trust) is to invest in financially sound, growing businesses that are making meaningful returns to shareholders. This results in a portfolio that generates a strong total return throughout market cycles; capital growth complemented by a stream of income.
Concentrating on these attributes means we invest in growth businesses that, without resorting to excessive borrowing, generate more cash than they require to grow, paying out the surplus to shareholders.
This approach helps us avoid value traps (companies that are cheap for a reason) and valuation extremes (dividend-paying companies tend to be less prone to boom-and-bust cycles and therefore deliver a more stable return through time) while limiting downside (a company with a strong financial position should be able to ride out hard times).
Start your trial of MoneyWeek today
Get unparalleled financial insight, analysis and expert opinion you can profit from.
Sign up for MoneyWeek’s free twice-daily newsletter.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
BayCurrent (Tokyo: 6532)is a consulting firm whose shares suffered a severe de-rating as confidence in their industry was rocked by the threat of AI. Japanese firms were treated with similar disdain to their international peers, but, as is often the case, Japan proved unique – more than 70% of IT professionals are employed by IT services/consulting firms, rather than directly by big corporations.
This is the reverse of the US situation, where companies have plenty of high-skilled employees to implement AI-driven enhancements. Japanese firms require external support and this is where BayCurrent comes in. Far from being a threat to its business model, AI has provided a tailwind – more 50% of its consultants' current projects are AI-related.
The market tarred all firms with the same brush and that gave us the chance to buy into a high-quality company growing its revenues by about 30% and at an attractive valuation.
JAC Recruitment (Tokyo: 2124) appears uniquely positioned in an industry under threat from wider use of AI. Japan's structural labour shortage is increasingly acute for mid-to-high-end roles, which is where JAC focuses its efforts. Greater labour mobility, the requirement to maintain job opportunities for an older age and newly created roles (such as non-executive directors) are all structural drivers of growth.
JAC concentrates on industries with strong long-term prospects, such as manufacturing and medical and financial services. We believe that the high-end focus and the specialist segments insulate the company from the challenges facing others in the sector, such as white-collar job losses. Management has shown a clear commitment to growing the dividend and the low capital intensity of the business allows it to give this a high priority.
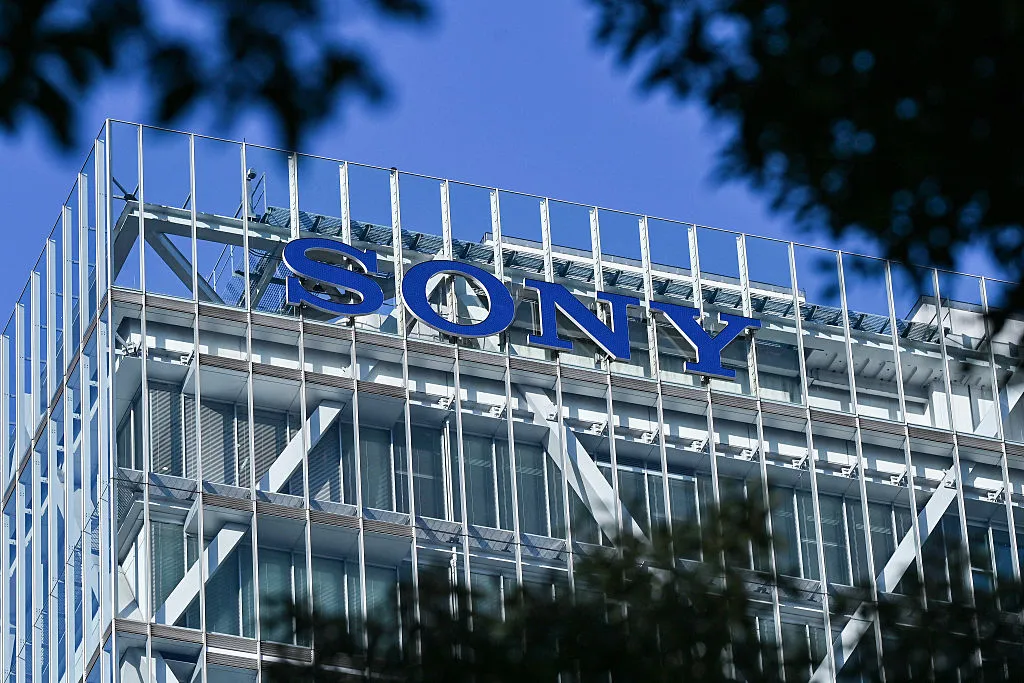
Sony (Tokyo: 6758) is a household electronics name that has transformed itself into an entertainment powerhouse. We have long admired the company, but until recently the rich valuation held us back.
Sony has been on the receiving end of the meteoric rise in the prices of memory chips, both in its console and image-sensor businesses. The latter is also an area of concern for the market as Sony supplies 100% of the high-end image sensors used in iPhone main cameras and is therefore exposed should Apple seek other sources.
A third reason for recent underperformance is the risk AI poses to the entertainment business. We feel the market is overly pessimistic in these regards, underestimating the quality of the business, its management team and the strong growth opportunity Sony presents.
This article was first published in MoneyWeek's magazine. Enjoy exclusive early access to news, opinion and analysis from our team of financial experts with a MoneyWeek subscription.
Sign up for MoneyWeek's newsletters
Join more than 165,000 subscribers and keep yourself informed with the latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.